October 14, 2026
October 14, 2026
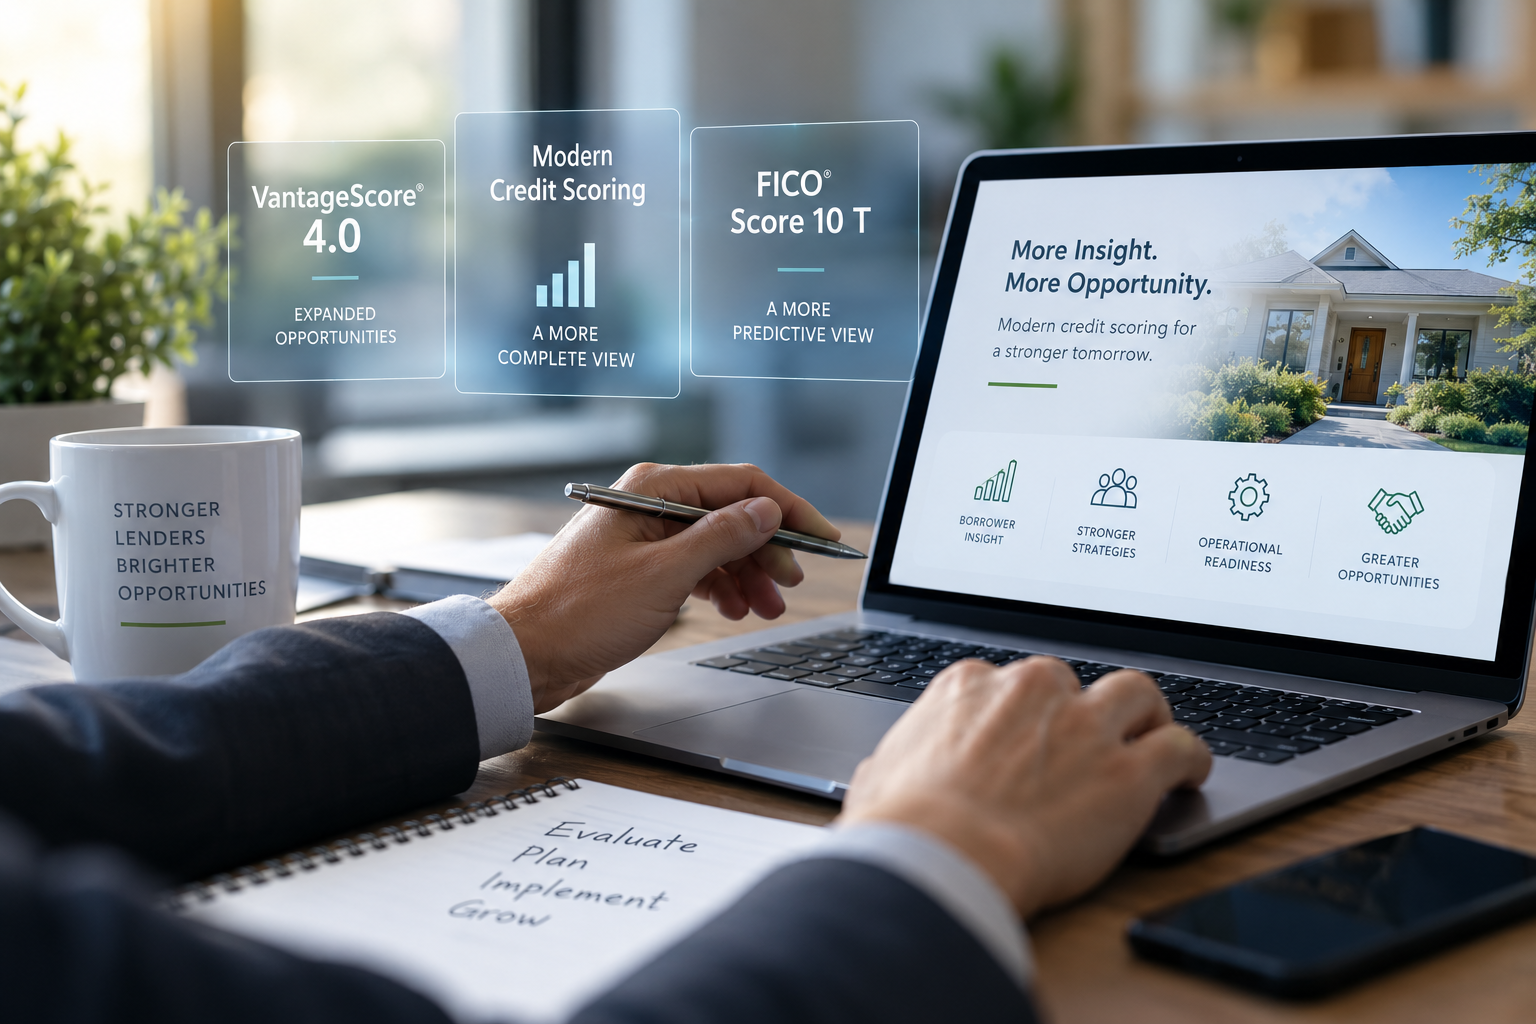
Mortgage credit scoring is changing, and lenders have more to consider than simply adopting a new score.
With VantageScore® 4.0 approved for use on eligible GSE loans and the mortgage industry preparing for FICO® Score 10 T, lenders have an opportunity to evaluate how modern credit scoring models may affect borrower assessment, lending strategies, workflows, and loan production.
At Birchwood Credit Services, we are helping lenders understand these changes and determine what they could mean for their specific borrower populations and business objectives.
FICO® Score 10 T and VantageScore® 4.0 are distinct credit scoring models, but both are part of a broader shift toward more modern credit risk assessment.
One important component is trended credit data, which provides information about a consumer's credit behavior over time rather than relying solely on a snapshot of current credit activity.
Consider two borrowers with similar balances today. One may have consistently paid balances down, while another may have steadily accumulated debt. Trended data can provide additional context around those patterns and how a consumer manages credit.
For mortgage lenders, that additional information can influence how borrower risk is evaluated and create new considerations for credit strategy.
The approval of VantageScore® 4.0 for eligible GSE loans has moved part of the credit score modernization conversation from preparation to implementation.
Lenders can evaluate how VantageScore® 4.0 fits within their existing operations, business goals, and borrower populations. Importantly, tri-merge credit reporting remains part of the process, allowing lenders to assess the model without automatically requiring a complete redesign of established credit reporting workflows.
VantageScore® 4.0 may also provide scoring opportunities for some consumers with limited traditional credit histories, giving lenders another reason to examine how the model could affect their borrower population.
The key question is not simply whether a new scoring model is available. It is where and how that model makes sense for your business.
At the same time, lenders should be preparing for FICO® Score 10 T and evaluating its potential impact before implementation decisions become urgent.
Birchwood has been actively assessing the implications of FICO® Score 10 T across trended credit data, score performance, lender workflows, operational processes, and borrower impact.
For lenders, preparation should include questions such as:
There will not necessarily be one answer that applies to every lender. Borrower populations, credit policies, products, technology, and business objectives differ.
That is why comparative score analysis can play an important role in preparing for credit score modernization.
Rather than making assumptions about how a new credit scoring model will affect production, lenders can evaluate actual scoring outcomes across their borrower populations.
Comparative score evaluations can help identify changes in score distributions, borrower segments that may experience meaningful differences, potential qualification or pricing implications, and areas where new lending opportunities could exist.
The impact of credit score modernization should be evaluated using data, not guesswork.
This analysis can also help lenders prepare internal stakeholders and determine where changes may be needed across credit policies, workflows, technology, training, and borrower communications.
Birchwood's role is not to tell lenders that one scoring model is the answer. We help lenders understand their options and make informed decisions based on their business and borrower populations.
Our team supports lenders through:
The goal is to help lenders move beyond simply reacting to credit score changes and develop a strategy grounded in their own data.
VantageScore® 4.0 and FICO® Score 10 T represent significant developments in mortgage credit score modernization.
For lenders, the opportunity is bigger than adopting a new model. It is understanding how evolving credit assessment can affect borrowers, risk, operations, and lending opportunities.
Birchwood is ready to help lenders evaluate VantageScore® 4.0, prepare for FICO® Score 10 T, compare potential scoring outcomes, and determine what these changes mean for their business.
Ready to evaluate your credit scoring strategy? Contact Birchwood Credit Services at 800.910.0015 to start the conversation.